


SurveysFeb 04, 2025
Valentine’s Day Jewelry Spending Forecast to Hit Record High, Says NRFSurveysFeb 10, 2025
Jewelry Resilient in 2024 Even As Luxury Sales Slipped, Says Bain & Co.
Bain & Co.’s latest report on the luxury market examines why the market’s customer base is shrinking and how to appeal to consumers in 2025.


An 18-karat yellow gold “Stilla” ring set with marquise and round diamonds by Tacori ($2,990). Bain & Company’s new “Luxury Goods Worldwide Market Study” examines how the market performed in 2024 and what’s ahead in 2025.
New York—Bain & Company’s “Luxury Goods Worldwide Market Study,” released last month in collaboration with Altagamma, shared insights into the 2024 luxury market and the outlook for the year ahead.
According to the study, sales in the global luxury goods market dipped to €1.48 trillion ($1.54 trillion) in 2024, down 1 to 3 percent year-over-year at current exchange rates.
This slight decline signifies a normalization after the strong growth seen in 2022 and 2023, said the report, with 2024’s performance still surpassing pre-COVID levels.
Bain & Co.’s report delves into the reasons behind the decline in sales last year, how the jewelry category is performing, U.S. market trends, and more.
Here are five takeaways from the report.
The luxury market’s customer base is shrinking.
For the first time in the 23-year history of this report, the luxury market’s customer base contracted.
Bain estimated the market lost about 50 million customers globally between 2022 and 2024, declining from 400 million to around 350 million customers by the end of 2024 driven by a decline in demand for personal luxury goods, particularly among younger consumers.
The market for personal luxury goods (e.g., jewelry, watches, clothes, cosmetics), which Bain called “the core of the core” of luxury segments, saw its first contraction in 15 years, excluding the pandemic period.
“Global luxury consumers, grappling with macroeconomic uncertainty and continued price elevation by brands, cut back slightly on discretionary items,” said the report.
The size of the market for personal luxury goods dipped 2 percent year-over-year at current exchange rates to €363 billion ($377 billion) in 2024.
“This trend—particularly acute among Generation Z, whose advocacy for luxury brands continued to decline—has caused the [overall] luxury customer base to shrink,” the reported noted.
The slowdown in the market led to polarized performances among luxury brands.
The report estimated only about one-third of brands saw growth in 2024, compared with 95 percent from 2021 to 2022 and 65 percent in 2023.
“The average profitability of personal luxury goods brands eroded, reflecting the limited room for further price increases and rising costs of serving the consumer, from marketing to distribution,” said the report.
By region, sales in the Americas totaled €100 billion ($103.86), down 1 percent year-over-year at current exchange rates.
The U.S. luxury market was on a “generally upward” quarterly trajectory throughout the year despite ebbs and flows in consumer confidence.
Aspirational customers are facing financial pressure, with more shoppers opting for value-for-money luxury and non-luxury brands, turning to department stores and outlet malls to do their shopping.
Shoppers, particularly younger ones, value “hyper-personalized” customer service and are looking for unique items.
A few factors should help to sustain the U.S. market’s performance in the future, said the report, including potential interest rate cuts by the Federal Reserve, the conclusion of the presidential election, easing inflation, and the prospect of tax cuts and enhanced economic growth.
Jewelry was the “most resilient” of the core luxury segments.
Though the overall market for personal luxury goods struggled, jewelry was a top performer, particularly in the United States.
Jewelry “proved to be the most resilient core luxury category in 2024,” said the report, flat to up 2 percent at current exchange rates to reach €31 billion ($32.2 billion) in sales.
“This performance was driven by consistent high-low brand strategies and enhanced customer-centric approaches,” said the report.
High jewelry did especially well, outperforming the “less-elevated” parts of the market.
“Competition intensified, with luxury fashion houses expanding their presence in the segment and rising local giants seeking to grow beyond their domestic markets,” it said.
Chanel, for example, introduced its “Haute Joaillerie Sport” high jewelry collection in 2024.
The report also noted that secondhand luxury is increasingly becoming a “gateway” to luxury for aspirational consumers who cannot afford new items, with growth in sales of pre-owned jewelry particularly strong and sales of secondhand clothing accelerating.
The success of the jewelry category is impressive when considering that few luxury categories posted growth in 2024.
The report said most, “experienced elevation-related volume declines due to list price increases and an emphasis on higher price categories in the mix of products sold.”
Outside of jewelry, luxury beauty and eyewear performed the best, up 3 to 5 percent year-over-year as customers opted for small indulgences and responded well to “renewed creativity” in the eyewear category.
Related stories will be right here …
According to the study, sales in the global luxury goods market dipped to €1.48 trillion ($1.54 trillion) in 2024, down 1 to 3 percent year-over-year at current exchange rates.
This slight decline signifies a normalization after the strong growth seen in 2022 and 2023, said the report, with 2024’s performance still surpassing pre-COVID levels.
Bain & Co.’s report delves into the reasons behind the decline in sales last year, how the jewelry category is performing, U.S. market trends, and more.
Here are five takeaways from the report.
The luxury market’s customer base is shrinking.
For the first time in the 23-year history of this report, the luxury market’s customer base contracted.
Bain estimated the market lost about 50 million customers globally between 2022 and 2024, declining from 400 million to around 350 million customers by the end of 2024 driven by a decline in demand for personal luxury goods, particularly among younger consumers.
The market for personal luxury goods (e.g., jewelry, watches, clothes, cosmetics), which Bain called “the core of the core” of luxury segments, saw its first contraction in 15 years, excluding the pandemic period.
“Global luxury consumers, grappling with macroeconomic uncertainty and continued price elevation by brands, cut back slightly on discretionary items,” said the report.
The size of the market for personal luxury goods dipped 2 percent year-over-year at current exchange rates to €363 billion ($377 billion) in 2024.
“This trend—particularly acute among Generation Z, whose advocacy for luxury brands continued to decline—has caused the [overall] luxury customer base to shrink,” the reported noted.
The slowdown in the market led to polarized performances among luxury brands.
The report estimated only about one-third of brands saw growth in 2024, compared with 95 percent from 2021 to 2022 and 65 percent in 2023.
“The average profitability of personal luxury goods brands eroded, reflecting the limited room for further price increases and rising costs of serving the consumer, from marketing to distribution,” said the report.
By region, sales in the Americas totaled €100 billion ($103.86), down 1 percent year-over-year at current exchange rates.
The U.S. luxury market was on a “generally upward” quarterly trajectory throughout the year despite ebbs and flows in consumer confidence.
Aspirational customers are facing financial pressure, with more shoppers opting for value-for-money luxury and non-luxury brands, turning to department stores and outlet malls to do their shopping.
Shoppers, particularly younger ones, value “hyper-personalized” customer service and are looking for unique items.
A few factors should help to sustain the U.S. market’s performance in the future, said the report, including potential interest rate cuts by the Federal Reserve, the conclusion of the presidential election, easing inflation, and the prospect of tax cuts and enhanced economic growth.
Jewelry was the “most resilient” of the core luxury segments.
Though the overall market for personal luxury goods struggled, jewelry was a top performer, particularly in the United States.
Jewelry “proved to be the most resilient core luxury category in 2024,” said the report, flat to up 2 percent at current exchange rates to reach €31 billion ($32.2 billion) in sales.
“This performance was driven by consistent high-low brand strategies and enhanced customer-centric approaches,” said the report.
High jewelry did especially well, outperforming the “less-elevated” parts of the market.
“Competition intensified, with luxury fashion houses expanding their presence in the segment and rising local giants seeking to grow beyond their domestic markets,” it said.
Chanel, for example, introduced its “Haute Joaillerie Sport” high jewelry collection in 2024.
The report also noted that secondhand luxury is increasingly becoming a “gateway” to luxury for aspirational consumers who cannot afford new items, with growth in sales of pre-owned jewelry particularly strong and sales of secondhand clothing accelerating.
The success of the jewelry category is impressive when considering that few luxury categories posted growth in 2024.
The report said most, “experienced elevation-related volume declines due to list price increases and an emphasis on higher price categories in the mix of products sold.”
Outside of jewelry, luxury beauty and eyewear performed the best, up 3 to 5 percent year-over-year as customers opted for small indulgences and responded well to “renewed creativity” in the eyewear category.
The watch category struggled as consumer interest waned.
Watches had a tough year, posting sales declines of 5 to 7 percent at current exchange rates to around €51 billion ($52.97 billion) in 2024.
“The segment exited its recent growth cycle amid reduced consumer interest, and prices dropped in the secondary market,” said the report.
Only top-performing brands saw positive results, it said, with demand for unique shapes and precious materials growing.
Notably, gender-specific designs were less common.
The report also noted that the “retailization” trend in distribution continued, with brands looking to build connections with customers in their own stores instead of relying on multi-brand distributors.
Outlet stores did well as shoppers looked for deals.
The outlet channel outperformed the market in 2024, posting a growth rate of 0 to 3 percent at current exchange rates, the report said.
While most physical luxury stores suffered from “plummeting” foot traffic, the outlet channel gained popularity as an entry point into the luxury market, driven in part by shoppers looking for more for their money.
“Aspirational consumers faced increased financial pressure, leading to a shift toward value-for-money luxury and non-luxury brands, particularly in department stores and outlet malls,” said the report.
As for the other channels, monobrand stores saw sales declines of 1 to 4 percent at current exchange rates, due in part to a decrease in foot traffic.
Multi-brand stores also struggled, with department store sales down 2 to 4 percent and specialty stores down by 4 to 8 percent.
As for online sales, the report said the channel is normalizing after post-pandemic swings, posting declines of 1 to 4 percent at current exchange rates. It maintained a 20 percent share of the luxury market.
Notably, off-price online platforms saw growth because they, “[serve] as a gateway to luxury purchases and an appealing alternative for affluent consumers trading down.”
To succeed in 2025, luxury retailers need a solid strategy.
Last year was a challenging one for the luxury sector, but this year could see growth.
The personal luxury goods segment is forecast to grow moderately in 2025, with sales estimated to be flat to up 4 percent.
The report said solid market fundamentals should lead to growth between 4 to 6 percent annually until 2030, reaching an estimated total value of €460 billion to €500 billion ($477.75 billion to $519.29 billion) by the end of the period.
Demographic and macroeconomic tailwinds should bolster the sector because, it said, there are more than 300 million new customers likely to emerge in the next five years in China and other markets.
Retailers may have some tough choices to make to navigate the issues facing the luxury industry, such as deciding whether to seek exclusivity or change course to reach a broader audience, but deciding on a strategy is the way forward, the report said.
“Across all the potential strategic choices, there’s a common need to rebuild luxury foundations by refocusing on the basics that have always characterized luxury, such as the highest quality and creativity; by fostering a relationship with consumers that goes beyond individual transactions, connects with multiple audiences, and transcends short-term hype; and, lastly, by delivering flawlessly, drawing on new technology such as generative AI along the whole value chain,” the report said.
Read the full report on the Bain & Company website.
Editors' Picks
Sponsored by


More on Surveys
The Latest

PodcastsOct 21, 2026
Episode 10: This Episode Is Haunted Diana Singer shared the stories of two “cursed” diamonds on this month’s podcast, which was inexplicably riddled with technical issues.

IndependentsOct 21, 2026
Gardner-Collier Jewelry to Close After 9 Decades in BusinessThe family-owned jeweler has three locations across Missouri and Iowa.
SourcingOct 21, 2026
Venetia Mines Final Carats Ahead of 2-Year ShutdownThe De Beers-owned diamond mine in South Africa is being put on ice as part of a round of previously announced cost-cutting measures.

Brought to you by
A Diamond Is Forever Launches 2026 Holiday Campaign Championing Natural DiamondsA Diamond Is Forever's holiday campaign reimagines natural diamond icons for a new generation celebrating individuality.

CollectionsOct 21, 2026
Helzberg, Nordstrom Carrying New Jewelry Collection From Off-WhiteThe collection centers designs with clean geometric lines, chunky sculptural pieces, and recognizable details from the luxury fashion brand.

Weekly QuizOct 15, 2026
This Week’s QuizTest your jewelry news knowledge by answering these questions.
SourcingOct 21, 2026
Gemfields’ Mixed-Quality Ruby Auction Earns $52MThe miner said it saw particularly strong prices for larger, fine-quality rubies at the sale.

CrimeOct 20, 2026
Security Guard Charged With Murder in Shooting at Texas MallThe guard opened fire on a man who was smashing a jewelry display case at La Gran Plaza in Fort Worth last week, police said.
Brought to you by
Open an Account, Get $50 Off Your First Order. No Code Needed.Built on Relationships. Refined by Craft.

IndependentsOct 20, 2026
David Gardner’s Jewelers Unveils Newly Expanded, Revamped ShowroomThe Texas jeweler added 2,000 square feet to its reimagined showroom, complete with a new design studio and an event space.
SourcingOct 20, 2026
The $50M Victoria’s Secret ‘Fantasy Bra’ By The NumbersJacob & Co.'s diamond masterpiece is the most expensive Fantasy Bra ever worn on the Victoria’s Secret Fashion Show runway.

CollectionsOct 20, 2026
Mignon Faget’s Collection Chooses Handmade Over AIThe “Atelier” collection was inspired by the tools, rituals, and objects in an artist’s studio as a quiet rebuttal to an automated world.
MajorsOct 19, 2026
The Knot to Acquire Rival Wedding Planning Platform ZolaThe pending acquisition is an “exciting opportunity” for wedding vendors to grow their business, said The Knot Worldwide’s CEO.
SourcingOct 19, 2026
Jewelry Design Competition Show Airs in Thailand"The Secret Gems" features eight Thai jewelry brands paired with a team of young craftspeople who create jewelry together to win challenges.

CollectionsOct 19, 2026
John Hardy Enters the Medallion Chat With Talisman Collection The brand’s “Modern Talisman” capsule collection introduces pendants inspired by the mythology, natural world, and spiritual ethos of Bali.
IndependentsOct 19, 2026
The Stories of 5 Jewelers Celebrating Their Centennials in 2026Independent jewelers from New Mexico to New Jersey answer the question: What has kept your store in business for 100 years?
CollectionsOct 16, 2026
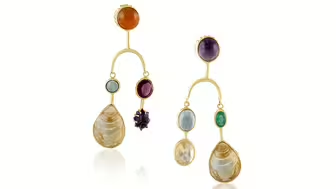
Christina Puchi’s Earrings Hold the UniverseOur Piece of the Week gathers the planets, represented by a variety of colored gemstones, in a pair of 14-karat yellow gold earrings.
IndependentsOct 16, 2026
Reeds Jewelers Expands, Relocates FlagshipThe New York-based jeweler is moving its Amherst flagship store to a larger location in nearby Snyder.
MajorsOct 16, 2026
Katy Chen Appointed Executive Vice President of Graff USA Chen, who worked at Cartier and Tiffany & Co., will lead retail sales and operations for the luxury jeweler’s 11 U.S. stores.
IndependentsOct 15, 2026
Retailer Hall of Fame 2026: Amy and Elise Greenberg For 40 years, sisters Amy and Elise Greenberg have helmed their 126-year-old family business, leading with appreciation and integrity.
ColumnistsOct 15, 2026
Peter Smith: What Is the Culture REP?It’s a term Smith coined and felt compelled to share following a bad experience with an aborted flight and an unfeeling flight attendant.

WatchesOct 15, 2026
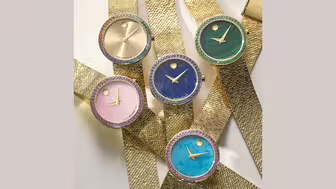
Stephanie Gottlieb’s New Movado Watches Are Made for Your Wrist StackMovado teamed up with the New York-based fine jewelry designer on a new collection of Movado Museum Velura watches.
SourcingOct 15, 2026
Signet Jewelers, Richemont May Join Bidder for De Beers, Report SaysThe two companies are reportedly in talks to join the Global Diamond Consortium, led by former De Beers CEO Gareth Penny, as per Bloomberg.
CollectionsOct 15, 2026
Wolf x Marla Aaron's New Jewelry Box Is for Some (Not All) of Your ThingsThe “Some of the Things” box follows the two larger “Everything” box designs with the look and function of antique sewing and toolboxes.
IndependentsOct 14, 2026
Retailer Hall of Fame 2026: Coleman and Mitchell ClarkFourth-generation jewelers Coleman and Mitchell Clark exemplify the best qualities of their predecessors: humility, modesty, and confidence.
SourcingOct 14, 2026
Manuel Marcial de Gomar, ‘The Emerald Whisperer,’ Dies at 90The gem hunter, whose 70-year career was defined by adventure and exploration, is remembered for his steadfast faith and sense of wonder.
FinancialsOct 14, 2026
LVMH’s Jewelry Brands Turn in ‘Very Good’ Performance in Q3 Tiffany & Co. continued its full-scale store renovation project while Bulgari’s high jewelry collection generated “record-breaking revenue.”
Events & AwardsOct 14, 2026
Chicago Responsible Jewelry Conference Releases 2026 ProgramThis year’s sessions feature leading voices from human rights, legal, and conservation organizations.


